

Disclaimer: This analysis is provided for informational purposes only and does not constitute investment advice. Forward-looking estimates are based on historical precedent and modeled scenarios; actual outcomes may differ materially.
Executive Summary
Vertiv Holdings (NYSE: VRT) has emerged as one of the most structurally advantaged beneficiaries of the AI infrastructure buildout. While investor attention concentrates on semiconductor companies, the physical layer of the AI economy — power distribution, thermal management, and facility infrastructure — has become the binding constraint on AI deployment at scale.
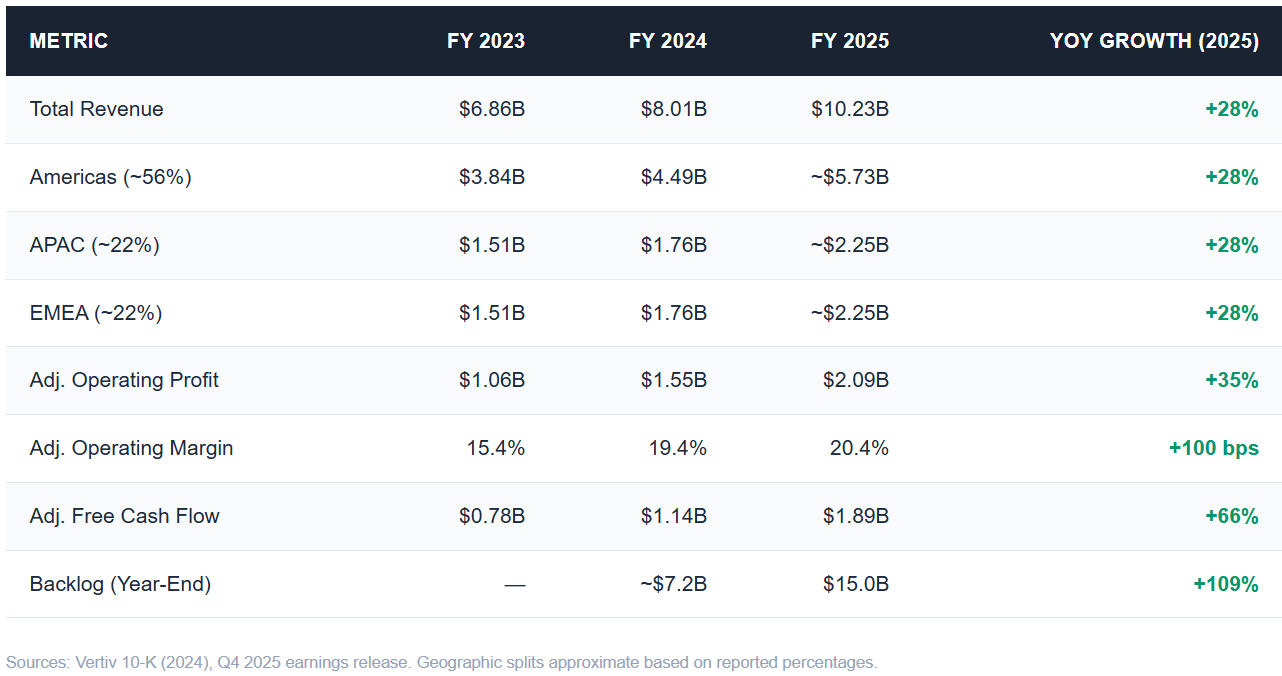
Vertiv’s full-year 2025 revenue reached $10.2 billion, up 28% year-over-year, with adjusted operating margins expanding to 20.4%. Organic orders surged 81% for the year, and the company exited 2025 with a backlog of $15.0 billion — more than a full year of revenue. Adjusted free cash flow reached $1.89 billion, up 66% from 2024.
The thesis is straightforward: AI compute requires 5–10x more power per rack than traditional workloads. Every dollar spent on GPUs creates derivative demand for power and cooling infrastructure. Vertiv, as one of two companies with meaningful global scale in data center power and thermal management, is positioned to capture a durable share of this derivative spend through 2030 and beyond.
This article introduces LongYield’s Hidden AI Winners series, which maps the full AI infrastructure stack to identify companies capturing critical economic value from the AI buildout beyond the obvious semiconductor beneficiaries.
Key Takeaways
Investment Highlights
AI rack densities have increased from ~8 kW (traditional) to 40–132 kW per rack, with next-generation systems targeting 250+ kW. This fundamentally changes the economics of data center power and cooling.
Hyperscaler capex is projected to reach ~$600 billion in 2026, up from ~$256 billion in 2024. Approximately 75% is directed toward AI infrastructure, creating a massive addressable market for power and thermal management.
Vertiv’s backlog of $15.0 billion at year-end 2025 provides exceptional revenue visibility. The Q4 2025 book-to-bill ratio of ~2.9x signals accelerating demand.
Adjusted operating margins expanded from ~15% in 2022 to 20.4% in 2025, demonstrating both pricing power and operating leverage. Management targets further expansion toward 22–24% over the medium term.
Vertiv’s co-development partnership with NVIDIA on GB200 NVL72 reference architectures positions the company as the default infrastructure partner for next-generation AI deployments.
At ~40x forward P/E, the stock is priced for growth — but the backlog and secular demand curve provide a margin of safety that most high-multiple industrials lack.
Introducing The Hidden AI Winners Series
The dominant narrative of the AI investment cycle has centered on a single company: NVIDIA. And for good reason — NVIDIA’s data center revenue has grown from $15 billion in fiscal 2024 to over $115 billion in fiscal 2025, making it the clearest direct beneficiary of the AI buildout. But NVIDIA is only one node in a vast and complex infrastructure stack, and the investment implications extend far beyond semiconductors.
Every GPU cluster requires power distribution systems to deliver clean, reliable electricity. Every high-density rack requires thermal management systems to remove the heat those GPUs generate. Every AI training run depends on high-bandwidth networking to connect thousands of accelerators. Every data center sits on real estate that must be permitted, built, and connected to the electrical grid.
These are not ancillary businesses. They are structural bottlenecks. The AI economy cannot scale without them, and the companies that control these chokepoints possess pricing power, recurring revenue streams, and competitive moats that are frequently underappreciated by the market.
LongYield’s Hidden AI Winners series is designed to systematically map these infrastructure layers and identify the companies that function as toll collectors, bottleneck providers, and critical enablers of the AI buildout. Each article in the series will focus on one company, examining its competitive position, financial trajectory, and durability of earnings within the AI infrastructure stack.
The question we ask of each company is the same: Is this business structurally positioned to capture durable profits from the AI buildout between 2025 and 2030?
We begin with Vertiv Holdings, because power and cooling represent the most acute physical constraint on AI deployment today.
The AI Infrastructure Bottleneck
The transition from traditional data center workloads to AI training and inference has fundamentally altered the physical requirements of compute infrastructure. The change is not incremental — it is an order-of-magnitude shift in power density, heat generation, and cooling complexity.
The Rack Density Revolution
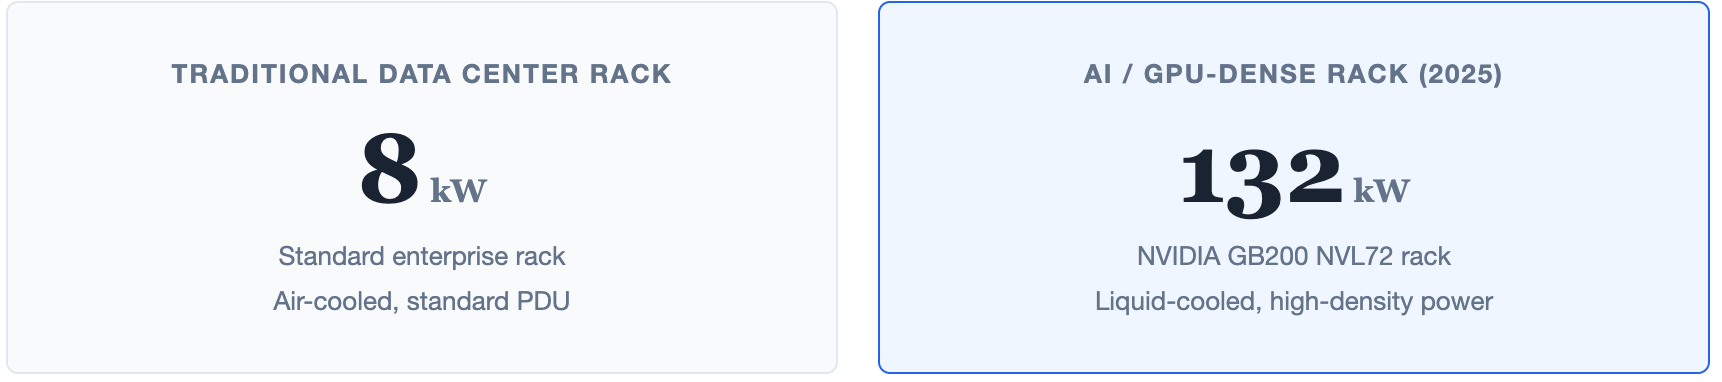
A traditional enterprise server rack consumed approximately 8 kW of power. Current AI-optimized racks using NVIDIA’s GB200 NVL72 architecture consume 132 kW — a 16.5x increase. Next-generation systems, including Blackwell Ultra and Rubin architectures, are expected to push rack densities to 250 kW and beyond, with NVIDIA’s roadmap pointing toward 1 MW per rack by 2027.
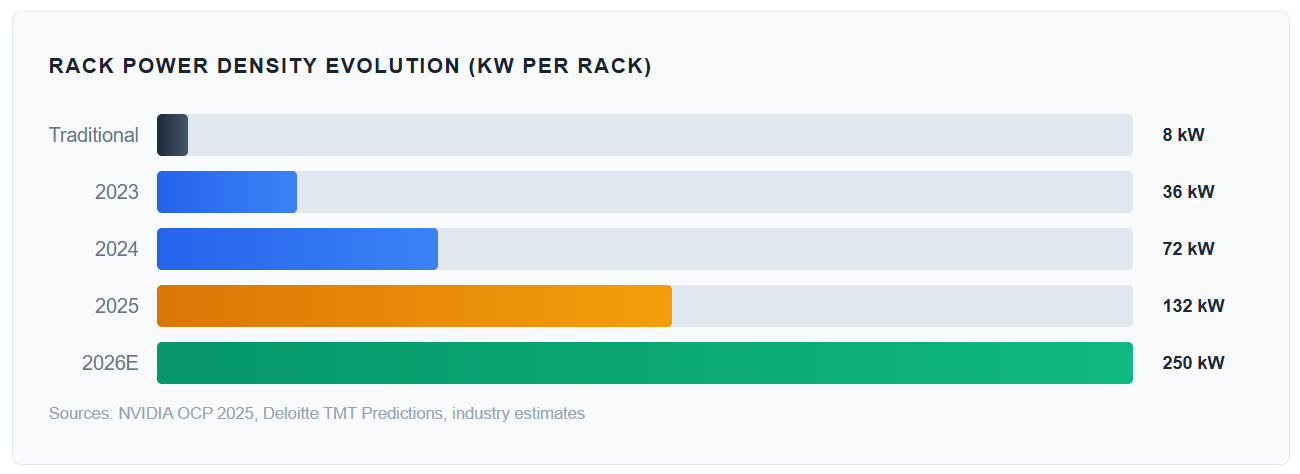
This power escalation creates two binding constraints. First, power delivery: data centers must source, distribute, and condition dramatically more electricity per square foot. Second, thermal management: at 132 kW per rack, traditional air cooling is physically inadequate. Liquid cooling — including direct-to-chip and rear-door heat exchangers — becomes a requirement, not an option.
Hyperscaler Capex: The Demand Signal
The capital expenditure commitments from the four major hyperscalers confirm the scale of this infrastructure buildout. Combined capex from Microsoft, Amazon, Google, and Meta is projected to reach approximately $600 billion in 2026, up from roughly $256 billion in 2024. Industry analysts estimate that approximately 75% of this spend is directed toward AI infrastructure.
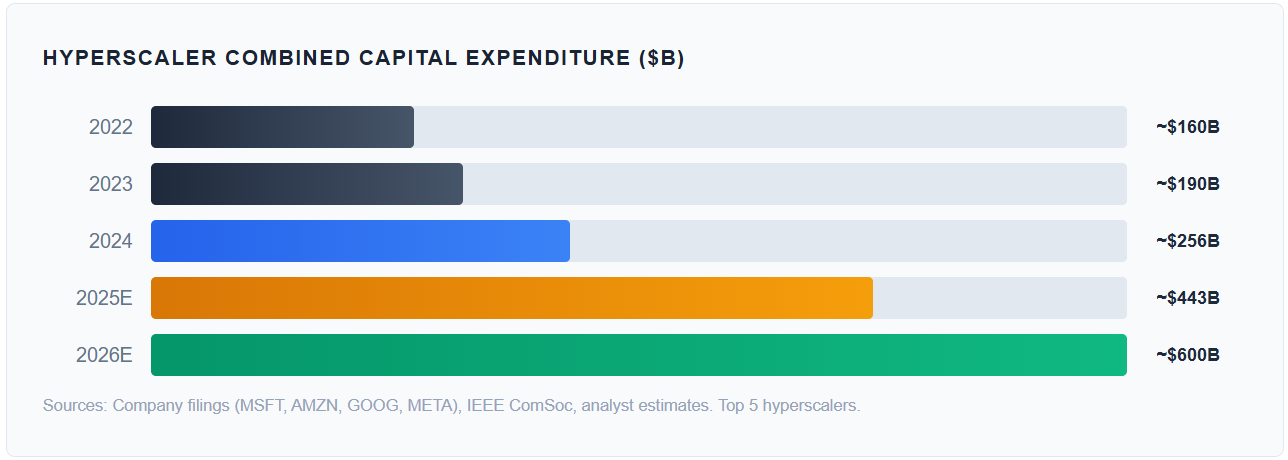
Critically, this capex is not discretionary. Hyperscalers are engaged in a competitive race to build AI capacity, and infrastructure lead times — particularly for power equipment and cooling systems — are measured in quarters, not weeks. This creates a demand profile that is both large and relatively inelastic in the near term.
Vertiv’s Business Model
Vertiv designs, manufactures, and services critical digital infrastructure for data centers, communication networks, and commercial and industrial environments. The business operates across three geographic segments — Americas, Asia Pacific (APAC), and Europe, Middle East & Africa (EMEA) — and generates revenue from both product sales and recurring service contracts.
The company’s product portfolio spans four core categories: power management (UPS systems, switchgear, power distribution units, busway), thermal management (precision cooling units, liquid cooling systems, containment solutions), IT infrastructure (racks, enclosures, integrated modular solutions), and services (maintenance, monitoring, lifecycle management).
A key feature of Vertiv’s model is the installed-base service business. With critical infrastructure deployed across thousands of data centers globally, Vertiv generates recurring service revenue through multi-year maintenance contracts, remote monitoring, and lifecycle services. This creates a predictable revenue stream and deepens customer relationships, making competitive displacement costly and operationally risky for customers.
